Thursday, April 21, 2022

Tambun Indah Land Berhad - Property Come Back??


Company : Tambun Indah Land Berhad


Business:

Small residential property developer in the mainland of Penang. The flagship development is Pearl city township which is near to Batu Kawan Industrial Park. The location is very strategic because of big tech firms are putting their factories in Batu Kawan industrial Park such as Vitrox, Pentamaster, Greatech and etc. The buying power should be strong as the employee of these companies are getting good pay.   


Fundamental:


 Financially healthy and no problem to pay dividen.


2021 revenue and profit surpass previous 3 years. The worst is over for the company and coming years should be profitable if company launch more developments with high take up rate.


Lates Q result:


Prospect:

  • The current take-up is 76% which is not bad for a developer.
  • Unbilled sales of RM131 million.
  • Close proximity to Batu Kawan which is next phase of growth for tech companies.
  • JF APEX- give target price of 93 cents.


Challenges:

  • Slow launch of projects
  • High building materials cost (cement/steel/etc)
  • Labour shortage


Dividen:


Dividen policy is 40% of its profit. Assuming 7 cents dividen that will translate to 7.7% yield based RM0.90 price. Much better than peer of Matrix concept.


Technical Analysis on Chart:


Suggest buying at consolidation stage and hold for 6 months to 1 year duration. Buy at your own risk.

I have been holding this stock for few years. To be honest it was a mistake that I made without proper analysis. I do not want to sell at lost so keeping it until now.

Wednesday, March 30, 2022

Mar 2022 Performance


SHARES ADDED

  • ATRIUM @ RM1.45
  • WellCall @ RM1.20
  • Pohuat @ RM1.40
  • United Plantation @ RM15.00

PACKAGING
Both BPPLAS and ThongGuan had released their Q4 results. Stellar performance but share price does not appreciated much. ThongGuan on the other hand drop due to resin price concern as Crude Oil already more than USD100 per barrel. I am not too concern as both companies are financially stable and will be able to pass on the resin cost to customers.

 
FURNITURE
Generally flat across the board. I added Pohuat as the company has successfully back to profit again from both Malaysia and Vietnam operations. The company has annouced 2 cents dividen. It will take at least 2-3 quarters before the price move up again. Hence this is good time to add Pohuat shares.


PLANTATION
My best earning in first quarter 2022 is from plantation. I added United Plantation for its stable dividen income (more than 7%) which ex-date is in April. The CPO price is still very high @ RM6000 per tonne due to supply shortage and Ukrain-Russia war. There is still room for share price appreciation as average CPO price last year was around RM5,000 for most plantation companies.


OTHER
SamChem and CSC Steel perform well. CSC Steel has appreciated more than 20% which suprised me.
FAVCO and Kawan do not changed much. They will need some time to appreciate.


FINANCE
ELK-DESA and Takaful are still flat. RCE has appreciated a bit. The dividen for ELK-DESA and RCE will come soon.

Friday, March 25, 2022

United Plantation - Sustainable Dividen?


Company : United Plantation – Sustainable Dividen?


Business:

Well established mid-sized plantation company with estates in Malaysia (71%) and Indonesia (29%). In Malaysia the estates are located in Perak and Selangor. In Indonesia, they are located in central Kalimantan. 90% of the estates are oil palm and remaining 10% are coconut. They have palm oil mills for their own FFB processing and oil refinery.


Fundamental:

Company has huge cash pile of RM478 million. Strong cash flow and no problem of giving dividen!


Revenue spike in 2021 due to high CPO price. Profit margin is pretty stable at average of 25%.


Challenges:

  • Shortage of labour which affect harvesting
  • Fertilizer price hike


Lates Q4 result:

This company does not issue Q4 result. Instead, they published annual report straight away. A bit confusing but this show how efficient they are!


Prospect:

The Ukraine-Russia war has an immediate effect on CPO because Ukraine and Russia are major sunflower oil producers. As a result of war, Ukraine cannot do farming and this will take at least 1 year to recover.

CPO price usually go in tandem with Crude Oil price. Due to sanction on Russia, oil price will remain high. High crude oil price will force Indonesia to curb their CPO export due to domestic demand and benefit Malaysia exporters. Complicated huh?


  • CPO price is record high. Even at RM5,000 per tonne. Company will make huge profit. Based on their report, their average selling price is only RM3,309 due to hedging.
  • Company practise hedging and therefore the risk of sudden drop of CPO will not have immediate effect on the company.
  • Technical know-how to drive production efficiency. See note from their annual report.


CPO YIELD IS HIGHER THAN PEERS


PEERS FFB & CPO YIELD


FORWARD SALES PRICE – HEDGING

Below note explains why their CPO selling price is lower than peers.


Very Interesting Fact of Palm Oil Vs Soy Bean Oil


 Dividen:

Dividen policy is 70-80% payout of its profit. This is very high compare other plantation company. In fact payout ratio for 2021 is a whopping 92%!!


Forecast Dividen for 2022 shall be at least 115 cent which is 7.6% based on current price of RM15.


 Technical Analysis on Chart:


At time of writing, I own UTDPLT shares. Buy at your own risk.


Saturday, March 5, 2022

Dancomech - Benefit from high CPO and Crude Oil ?


Company : Dancomech – Benefits from High Crude Oil and CPO?

 Business:

Manufacture of pumps and trading of valves, pump, gauges and recorders in oleochemical, Oil & Gas, water and wastewater and HVAC industries. This is mainly for plants maintenance purpose.

The trading division contribute 70% of the group revenue which is mainly from Oil and Gas and Oleochemical. Company also diversified to metal stamping business by acquiring MTL company in 2020 that produce tools and die.


A small cap company. It has been chosen as Asia’s 200 best under a billion company but not sure this is relevant to their actual share performance.


Fundamental

Company is in net cash position with clear growth of revenue. However, the CAGR-PAT is very small and profit margin is single digit at 8%.


Past 5 years revenue record show a clear trend of growth. Profit margin is declining especially in 2021. Based on their annual report, revenue growth is because of acquired metal stamping business, electronic, electrical & instrumentation. Despite revenue almost double, the profit after tax increase is very small (RM0.3 million).  


Lates Q4 result:


Q4 revenue increase and profit margin slightly improved.


Prospect:

  • Potential benefit from high CPO and crude oil price that allows plants to spend more on maintenance.
  • Revenue contribution from Metal Stamping business, Material handling Solution and E&E division are yet to reflect fully in FY 2021.


 Dividen:


Dividen payout ratio is 35% of its profit.


Technical Analysis on Chart:


Share price on downward trend because of the Warrant is about to expire. Hence adding more mother shares to the market. It seems like high risk and high volatile company.

 I don’t have Dancomech shares but good to monitor their performance especially profit after tax in Q1.


Monday, February 28, 2022

Feb 22 Performance

SHARES ADDED

  • Thong Guan @ RM2.60
  • MagniTech @ RM1.93 @ RM1.97 @ RM1.99
  • ATRIUM @ RM1.47
  • FAVCO @ RM2.50 @ RM2.55
  • KAWAN @ RM1.67

PACKAGING
BPPLAS profit improved QoQ and YoY. Share price increase 13%. Thong Guan on the other hand dropped to -5%. The Q4 result from Thong Guan is yet to release.

 
FURNITURE
LiiHen annouced 3.5 cent dividen. Q4 profit improved by 165% compared to Q3. The worst is probably over but still have issue like labour, resin cost and high shipment cost.  Pohuat is flat but notably investment guru, COLD EYE has emerged as top 30 shareholders. It is good time to add Pohuat!


PLANTATION
Both INNOPRISE and HSPlant are star performers this month. Superb profit and revenue due to high CPO price. HSPlant announced 15.5 cent dividen and share price spike to RM2.89 with an appreciation of 50%. INNOPRISE announced 6 cent dividen and share price rocketed to RM 2.01 with an appreciation of 72%.

I dispose all HSPLAN share and two third of INNOPRISE shares. Capturing profit of 35% for HSPLANT and average of 52% for INNOPRISE.  

Lesson to be learned here is to capturing maximum profit. So timing is important. Usually share price will soar for few days or weeks if all sentiments are good.

  
OTHER
SamChem and CSC Steel perform well. Share price improved by 19% and 18% respectively. Both counters registered profit improvement on Q4. CSCSteel declared 14 cents dividen, higher than expected. Samchem declared 1.5 cent. Proft taking activity took place at RM1.00. However, SamChem is good for long term growth and may accumalate when price drop below RM0.90.

New kids on the block are FAVCO and KAWAN. FAVCO has announced 8 cents ( a bit disappointed). KAWAN Q4 result is yet to release.

FINANCE
No surprise from finance sector except better result in Takaful. RCE and ELK-DESA are flat.


Wednesday, February 16, 2022

Favelle Favco - Benefit from Oil & Gas Recovery?


Company : FAVELLE FAVCO – Benefit from Rising Oil Price?

Business:

Manufacture cranes and intelligent automation for Oil & Gas under Exact group. Revenue split is approximately 77% for cranes and 23% for automation. Their business is highly expose to Oil & Gas, shipyard and high rise building. The crane business has foothold in USA, Europe, Middle East and Asia.


Fundamental:

Company has huge cash pile of over RM300 million so no problem to pay dividen every year.


Low profit margin and almost no growth in terms of CAGR revenue and PAT. This is partly due to slump of Oil & Gas sector.


Revenue stagnant at around 550 million and profit margin is compressed.


Lates Q3 result:


PROSPECT


There are few positive things on FAVCO.

  • Recovery of Oil price – especially Ukraine-Russia tension
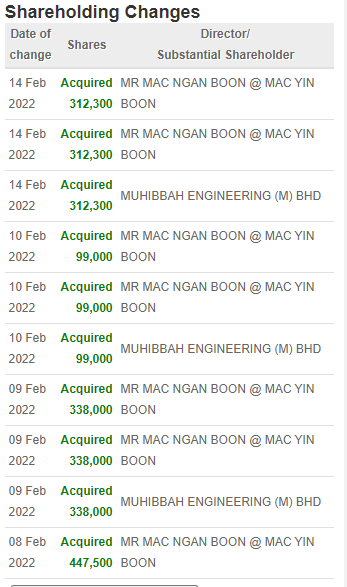
  • Shareholder share buy back recently


Revenue Split


58% of the revenue are generated outside from Malaysia. Automation is 100% from Malaysia.


Dividen:


No clear dividen policy but it is about 40% and once a year. Hopefully it can go back to 15 cent which will give 6% yield based on RM2.50


Technical Analysis on Chart:


Price does not fluctuate much and possible to go back pre-Covid level of RM2.80 – RM3.00 if Oil & Gas industry recover well.

At time of writing, I have some FAVCO shares.

Wednesday, February 2, 2022

Jan 22 Performance

SHARES ADDED

  • Hevea (average down)
  • MagniTech
  • WellCall (Top up @ RM1.20)
  • CSC Steel (@RM1.30)

PACKAGING
Packaging generally flat. Hopefully Q4 results will be good and expecting some dividen from both companies.

 
FURNITURE
LiiHen sprang a surprise by annoucing bonus issue of 2 for 1. Share price jumped 30 cents from RM2.70 when bonuse issue was announced.  Poh Huat remain flat. Hevea is still hovering around 46 cents. Price seems to be stable at this range and hence decided to average down by adding some more shares.

PLANTATION
Both INNOPRISE and HSPlant look good as dividen is coming soon. HSPlant may annouce higher dividen as profit is reaching record high.  

OTHER
SamChem is good for technical play. Price is trending up and will take profit when reach RM1.00.
CSC Steel is another technical play with 7 cent dividen coming. WellCall has pulled back after appreciated about 30%. Price down to RM1.20 and managed to top up some at this level. Since then price going up again to RM1.26. WellCall is constantly paying out dividen. ATRIUM has annouced Q4 results and 2.55 cent dividen. 


FINANCE
This sector is flat. RCE has been dropping after bonus issue. Takaful is no change but 12 cents dividen has been received in January 2022.