Sunday, September 11, 2022

BPPLAS - Next Wave of Rise

 Ah Pek company is on the rise again!!

I am checking on BPPLAS again after their latest Q2 result and the recent chart pattern. I won’t go into company fundamentals but below are the bullet points for easy reference.

  • Net cash company
  • Dividen every quarter
  • Expansion on production
  • Low resin price (low crude oil price)
  • Benefit from USD appreciation (export)
  • Chart Indicator (uptrend signal)

All are conducive for next phases of growth. Come on Ah Pek !


Friday, August 12, 2022

HEVEA UPDATE - 12 AUGUST

I have been holding Hevea for more than a year. Apart from dividen received, the share price is not exciting. In fact, dropping due to interest rate hike, rising resin price and inflation pressure.

However, it is not all that bad if we look into the fundamental. Company is cash rich and no issue with interest rate hike. Strong USD only benefit HEVEA as they are exporter. The input costs such as rubber wood and resin (glue) are in MYR.

Bulk of the business is from East Asia (Japan) and very small portion from USA. Hence, the impact on Hevea is very small.   


The Jan- May 2022 fibreboard export is increasing.


Source from MTC

I anticipate good 2nd quarter result from Hevea. Let’s see.

Down side risk seems limited.

At time of writing I own some Hevea shares. Buy at your own risk.


Tuesday, July 5, 2022

June 2022 - Performance

Date :

5-Jul-22

PACKAGING

Avg buying price

Last closed price

% Gain/Loss

THONG GUAN

2.540

2.270

-11%

BPPLAS

1.456

1.250

-14%

FURNITURE


POH HUAT

1.410

1.360

-4%

LIIHEN

0.981

0.900

-8%

HEVEA

0.499

0.435

-13%

PLANTATION


INNOPRISE

1.234

1.310

6%

UNITED PLANTATION

14.697

14.000

-5%

OTHERS


SAMCHEM

0.837

0.735

-12%

MAGNI

1.954

1.910

-2%

KAWAN

1.658

1.640

-1%

WELLCAL

1.108

1.150

4%

FINANCIAL


RCE CAPITAL *

1.022

1.670

63%

ELK-DESA

1.350

1.300

-4%

TAKAFUL

3.645

3.150

-14%


SHARES ADDED
  • INNOPRISE @ RM1.35

PACKAGING
Share price already reflected. Currrent high crude oil result in high resin price. Earning is affected. 

 
FURNITURE
Pohuat earning beated forecast. However, overall sector is done due inflation that will dampen the sales. Liihen has bonus issue which make the price lower. 


PLANTATION
This sector is down because of lower CPO price. I am still optimistic about INNOPRISE and UTDPLT. Both having free cash flow. It is time accumulate both stocks.


OTHER
Dispose CSC Steel and make some good profits. Dispose FAVCO as well but lower proft. KAWAN and SAMCHEM are on down trend because of bad market sentiment.

FINANCE
ELK-DESA and TAKAFUL are poor performers. Very disappointed especially Takaful.  It is bad investment fo TAKAFUL.

Thursday, June 16, 2022

INNOPRISE - Can We Still Invest?

Fundamental :

Company has no bank borrowing as at 31st December 2020. They have adopted a dividen policy of distributing 80% of the profit after tax. Revenue is cyclic as palm oil is commodity.


Q1 Result


Two major factors are CPO price and Production. I take the conservative 80% production output from the average of 2020 & 2021. Based on this production rate, let’s see how the CPO price will affect the earning per share and the dividen yield.

The EPS is generated using the formula that developed. It is not 100% but give very good indication.


CPO on Downtrend


The CPO down trend will continue as Indonesia cutting the export duty and putting more CPO supply to the market. Coming good harvest of Soybean in Latin America will also help to ease the supply shortage. Hence, I estimate that CPO will probably drop in between 3000-4000 level.

Based on this CPO level and dividen yield return, the price to enter is around RM1.36-RM1.50.


Stock Price on Down trend


Price already drops below the support level and will continue to drop. The bearish continue trend has shown.


At time of writing, I own some INNOPRISE shares @ low price. Waiting for opportunity to buy more.


Tuesday, June 7, 2022

FAVCO - Lesson Learn

FAVCO announced a whopping 85 cents per share on 6 May 2022. Price shot up to RM3.25 immediately.

Many investors trapped or lose money when buying at high sides @ RM3.25. Here is my view on what we can learn from the this incident. The selling time is important to avoid being trapped.


Motive of Huge Dividen

The motive of such high dividen was very clear. Muhibbah is the biggest shareholder of FAVCO and they are in cash flow problem. FAVCO has huge cash file. So naturally Muhibbah would want to utilize the cash pile from FAVCO. So the huge dividen is to save Muhibbah and not for rewarding shareholders because of good business.

In some cases, huge dividen also can happen if the company sold their core business. For example : SCGM who sold their plastic business to Mitsui Japan. 


Share Price

Share price will naturally adjust after ex-date. A lot people do not aware of such incident.  Share price also under huge selling pressure after ex-date. In many cases, prices go down FAR MORE THAN DIVIDEN itself. Unless your entry price is supper low or the company businsess will continue to be good, there is not point of holding the shares.


Strategy 

I have FAVCO share before the announcement of huge dividen which I could make appox 30% profit. However, I made a mistake of not selling it as I thought it had not reached the profit that I wanted. I also anticipated that business will continue to be good as oil price has recovered to USD100 per barrel. However, the QR was a disappointment. I ended up selling after dividen ex-date and made only small profit overall.

So the lesson is to sell before ex-date or sell half the shares if you anticipated good result or business will be good.


Wednesday, May 11, 2022

Company Setup in Malaysia

Due to reasons that cannot be avoided, I have to setup an entity or company in Malaysia to receive my remuneration. It is a lot of work but same time gives me an opportunity to learn various matters related to business such as account, tax planning, payrolls etc. I would to share the findings here for knowledge purpose. 


There are 3 types of setup in Malaysia. They are as follows:
  • Sole Proprietor / Pemilik Tunggal 
  • Limited Liability Partnership (LLP) /  Perkongsian Liabiliti Terhad (PLT) 
  • Private Limited / Sendirian Berhad.  

The differences of these 3 setups can be listed as follows:
  • Registration Setup
  • Liability
  • Tax planning 
  • Compliance
  • Cost
  • Strike off / winding up

Table below is a simple summary of different setup. 


SSM website provide a good comparison of the setup. You may visit their website below:

https://www.ssm.com.my/Pages/Register_Business_Company_LLP/Business/Before-Starting-Business.aspx


Depending on your business size, you may choose the setup that suits you. For example, if a small trader may opt for Sole Proprietorship at the beginning. If the bussines is doing well and consistent, it is best to switch to the private limited. The reasons are as follow:
  • Lower tax rate
  • Limited liability 
  • Better compliance to authority
Although the maintenance cost of a private limited is much higher than sole proprieter, the lower tax rate for private limited will balance out. We can look intot the tax rate of each setup in my next article for better understanding.

PLT is more for professional services such accountants, lawyer, auditors, company secretary and etc. This is purely my personal opinion as services does not required stock/product. 

Although PLT seems attractive in terms of tax rates, the complicate procedures to register and strike off is a hindrance. Besides most banks are still not favourable to PLT in terms of providing loan.

Another point to consider here is the tax compliance. Since the account of sole proprietor and PLT does not required audit, many mistakes will occur if the owners are not knowledagble on tax compliance. There will be heavy penalty to pay if mistakes are made.

Note : A private limited company now can have single director.


Wednesday, May 4, 2022

Malaysia Furniture - Recovery or Mini Boom?

 Malaysia Furniture – Recovery or Mini Boom?

Malaysia furniture and timber listed companies are quite a few in Bursa. Most of the companies are export oriented. With strengthening of US Dollar and recovery of our manufacturing sector, it is time to look at this sector and some companies as a whole.


According to Malaysia Timber Council, Malaysia timber export in 2021 is valued at RM22.744 billion. In particular wood furniture has a clear trend of growing mainly due to US-China trade dispute since 2019.


Malaysia Timber Council : http://mtc.com.my/resources-TradeInfo.php 


Malaysia Timber Export in MYR Million


USA has become the largest export market for Malaysia furniture makers since 2019 US-China trade war.


Factors affecting the industry:

  • Raw material – rubberwood
  • Raw material – adhesive (UF) – related to crude oil & more to fibreboard players.
  • Labour cost and shortage – Minimum wages of MYR 1,500 impact.
  • Shipping cost – related to crude oil and pandemic lockdown
  • USD-MYR currency


UREA Price Chart


Positive Signs:

  • Export increase in the first two months of 2022 – refer to Malaysia Timber Council
  • China lockdown which resulted in severe port congestion
  • USD-MYR favourable for exporters although not much
  • USA-China trade war, USA-Canada trade war, Ukraine-Russa conflict (Russia banning export to West)
  • Easing of labour shortage in Malaysia


Analysis by HLIB is upbeat on timber counter.

https://www.klsescreener.com/v2/news/view/973553/boom-in-wood-manufacturing-sector

Malaysia Export increase – Jan-Feb 2022 


Quick Summary

For furniture sector, I like Pohuat and Liihen for the consistence dividen payout. Latitud and Pohuat have overseas operations which are not affected so much of the minimum wages hike. Pohuat, Liihen and Latitude have 90% export to USA market. Interesting to know that most furniture exporters are cash rich companies.


Another set players are particle board manufacturers such as Hevea, Evergreen, MIECO and Focus lumber. Hevea is cash rich company and export to premium market like Japan. Its share price still is still a lagger compared to Evergreen and MIECO. Focus lumber is the only veneer supplier to USA market and commanding higher profit margin. It’s share price has appreciated a lot. I prefer Hevea as it is still a lagger.   


Malaysia is top 10 exporter according to MFI(not sure if this true). See below


Charts

Furniture Players

LiiHen

Potential Increase :          RM3.70


Pohuat

Potential Increase :          RM1.80


Latitud

Potential Increase :          RM1.90


MDF players

Hevea

Potential Increase :  RM 0.65


MIECO

Potential Increase :          RM 0.73


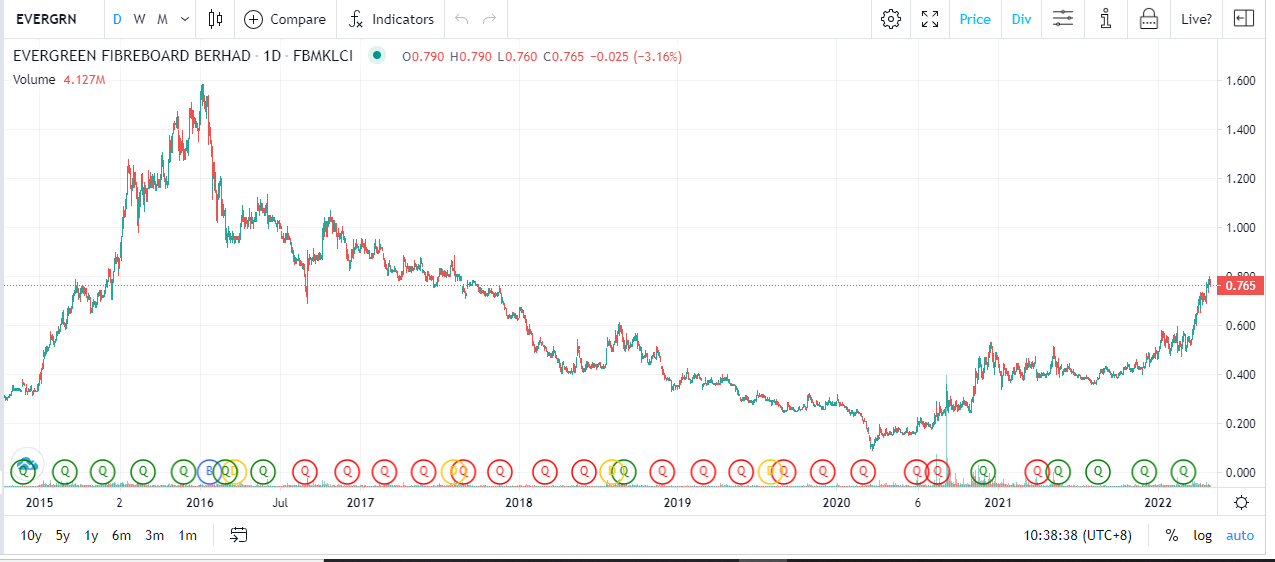
Evergreen

Potential Increase :          RM1.00