Friday, August 6, 2021

ATRIUM REIT - Small but Beautiful


Company : ATRIUM REIT

Business :

Industrial real estate investment trust (REIT). One of the few industrial REITs in Malaysia apart from Axis REIT. The characteristic of REIT is distribution of 90% of their rental income. Rental income is depending on the tenant quality and tenancy term. Rental income will not change so much except for rental revision, new acquisition of property or lost of tenants.   


Side Note:

The size and variety of Malaysia REIT (M-REIT) is far lack behind than Singapore REIT (S-REIT). M-REITs are still focusing on malls, office and some industrial whereas S-REIT have malls, offices, healthcare, industrial, warehouse, utilities and data centres. SGX is a hub for many international REIT companies go for listings.


5 years revenue:

An increasing trend of revenue due to more assets added to its portfolio.


Portfolio breakdown of the properties are as follow:

They have added another property Shah Alam 4 which is currently under renovation.


Tenant quality & occupancy:

Current occupancy is 100%. Most of the tenants seem stable and for mid to long term business.


Location and quality of property:

Locations of the properties seems good and well connected to major highways.


Supply and Demand of the Properties

The demand for industrial property seems good due to the growth of eCommerce.


Gearing

Currently gearing ratio is 42%.


Latest property at a glance:

Property Name

Customer

Property Use

Customer

Expiry

Shah Alam 1

Ninja Logistic

Factory & office

Logistic

1 Jun 2027

Shah Alam 2

Samsung SDS

Warehouse & office

MNC

31 Mar 2024

Shah Alam 3

Agility Logistic

Warehouse & office

Logistic

24 July 2021

Shah Alam 4

Upgrade

Upgrade

Nil

Nil

Bayan Lepas 1

Lumileds

Factory & office

Industrial

21 Oct 2035

Bayan Lepas 2

Lumileds

Factory & office


6 Oct 2034

Puchong

Lazada

Warehouse & office

E commerce

30 Sept 2023

USJ

Rohlig Malaysia (A)

Rohlig Malaysoa (B)

Skynet Worldwide (C)

Warehouse & office

Industrial

Industial

Logistic

31 Aug 2023

16 Feb 2024

31 Jul 2022


Risk of litigation:


Prospect:

There are few points that I like Atrium REIT.

  • Industrial REIT is less affected by COVID compared to malls.
  • Strategy locations of the properties.
  • 100% occupancy and long expiry. USJ tenancy for Skynet is very small.
  • Tenants are pretty good quality.
  • 6% dividen yield
  • Potential of extra rental income if Shah Alam 4 is rented out.


My view on share price:

Price has risen substantially from Feb 2021 to all time high of RM1.55. This is probably due to increase of income distribution since Q4 2020. The support level is RM1.42 and coming ex-date for Q2 income distribution is 11 Aug 2021. Typically share appreciation for REIT is very slow unless there is new property aquisition.


Forecast earning & PE.

Current PE is 13.20 at price RM1.46 (2 Aug 2021). Forecast EPS is 11.11 cent for whole year 2021. Hence price is still the same at RM1.46   


Q1

Q2

Q3

Q4

Total

3.19

2.64

2.64

2.64

11.11


Forecast dividen for whole year is 9.7 cent which is more than 6% yield. Higher than bank FD and EPF. As REIT is for stable dividen, the strategy is to park some funds here while waiting for other good opportunities arise.


At time of writing, I own ATRIUM REIT share. 


Friday, July 30, 2021

RCE Capital Berhad _ Robust Money Lending Business


Company : RCE Capital Berhad

Business :

Money lending (personal financing) to government servants. A subsidiary of Amcorp Group. This is good business as payment is very secured (direct debit from salary). The profit margin is a whopping 45% !! Mana cari this kind business model?


 5 years revenue, profits and earning per share.


Q4 Result


Consistence revenue and profit for FY 2021. Hopefully they can maintain RM34 million profit every quarter throughout FY 2022.


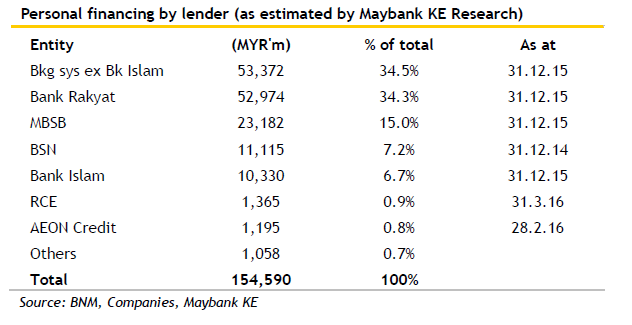
The write-up by Maybank Investment bank (sometime ago) is very interesting. RCE Cap has a very similar business model to AEON Credit.


Prospect:

They are bidding for digital banking license with a consortium together with Star Media Group and Paramount Corp but I think chances are low. The low interest environment is good for RCE as it brings down their cost of funds. See below.


Malaysia emoluments for Government sector is growing every year and this bode well for RCE business. See chart below.


My view on share price:

Price has risen from mid Nov 2020 to all time of RM3.00 around June 2021. It is then dropped to current price of RM2.74. The support level is around RM2.55-RM2.60 and this is a good entry if you wish to buy some.


Dividen payout is pretty consistence and increasing every year from 2017. Forecast for FY 22 will be 14 cents.


Forecast earning & PE.

Current PE is 8.5 at RM2.74 (23 July 2021) and forecast EPS for FY2022 is 37 cents. So fair value should be RM 3.14 ! The coming Q1 result is very important indicator for FY2022 share price.

Q1

Q2

Q3

Q4

Total

9.0

9.0

9.5

9.5

37


This is one of the companies that invested by famous local investor, Cold Eye (I read most of his books).  At time of writing, I own RCE Capital shares for some time and will continue to keep till maximum appreciation.


Friday, July 23, 2021

Thong Guan Berhad - 888!


Company : Thong Guan Industries Berhad 

Business :

Manufacturing of various plastics such stretch films, garbage bags, PVC food wraps, courier bags and compounding. The products are for different industries like the F&B, Industrial & packaging, Transport & logistic, Consumer packaging, hygiene & medical, retail & E commerce and waste & energy. I like the diversification. They are also selling tea & coffee and organic noodles.

Production facilities are in Malaysia, Thailand (30%JV) and China (Suzhou) … coming Myanmar (don’t know when). They are largest exporter of garbage bag to Japan market (12% share). Total output is more than 150,000 MT per annum. TGuan is one of the key plastic players. Revenue is just behind Scientex who has 400,000 MT


Fundamental :

Company has net cash of RM147 million. Very strong financial position. The 10 years track record are as follow and you can notice the revenue is increasing over years and company has a vision to achieve next RM billion revenue. I think the RM 1 billion target this year is achievable as Q1 result already achieved RM 282 million!


10 years revenue - record


Export business:

The split between export and local for plastic is 80% to 20%.


Geographical Breakdown:

Export to 70 countries. No information of breakdown in each country.


Quick comments on 2020 sales performance.


Stretch film – RM11.1 milion increase (2.6% increase)

Courier bag – RM12.9 million increase (26.9% increase!!)

F&B – RM14.3 million increase (22.8%)

A significant increase on the courier bag business which is a boom sector and glad that company is capturing this opportunity. Well done! The courier bag is for E commerce customer in USA. PVC Food wrap business was hit by pandemic but will recover soon. Garbage bag sales is slow in Japan.


Q1 Result:


Major plastic products sales are improving except PVC food wraps.


Prospect:

Existing capacity of the plastic division:

Category

Stretch Films

Industrial Film/bags

Garbage Bags

PVC Food wrap

Courier Bags

Existing machines

10 Conventional

5th Nano

3 Co-ex blow films

200 blow films

12 lines

?

Capacity

100,000 MT

?

33,000 MT

14,000 MT

7,200 MT

Immediate

Expansion

6th Nano line

(Total 5 more)

4th blow film


?

(10 lines by 2022)

14,400 MT by 2021

Contribution

45%

16%

16%

5%

6%


 Raw material effect:

Seem not much affected by the rising resin price. They have no problem passing the resin price hike to customers according to the director. Volume is a key advantage against the rest of competitors for better bulk price discount.


Growth opportunity:

Below is the next key phase of growth. It seems there is vision to achieve the next RM billion. Very interesting expansion plan.


You can watch the chat with the director via link below.

https://www.youtube.com/watch?v=U3LSme3RmQQ&t=3767s


My view on share price:


Forecast earning & PE.

In terms of earning, a quick estimate as below:

Q1

Q2

Q3

Q4

Total

5.71

5.5

5.5

5.5

22.21


Estimate full year PE is 11.53 at RM2.56 (22/7/2022). There is some room to appreciate if valuation is at PE 12.35 which will be RM2.74. Let’s wait and see. Scale of production will be a game changer and possible another Scientex company in the making. Set back is low dividen yield but that’s OK, you need time to grow Musang King or Black Thorn!

 At time of writing, I own TGuan shares and will keep it for long term. Hopefully the Ang’s family will not disappointed me. Buy at your own risk.

Note: Updates will be in FB page (mandarin version) below:

https://www.facebook.com/股海捞真-102714428734096